Amortization systematically retires debt through structured periodic installments split between interest and principal. While fixed monthly annuities (PMT) stabilize household cash flow by standardizing debt service across the term, equal principal reduction cuts aggregate lifetime interest by up to 18% to 22% by aggressively paying down capital from month one.
- Fixed annuity payments conceal front-loaded interest: on a 30-year 6.50% note, over 70% of early payments service pure interest rather than equity.
- Equal principal schedules demand 20% to 30% higher initial qualifying income but yield immediate debt relief and zero negative amortization risk.
- Prepaying just one extra monthly installment annually into principal curtails a standard 30-year mortgage by 4.2 to 4.8 years.
Loan Amortization Calculator
Generate complete monthly loan amortization schedule, principal payoff, and total interest.
The Actuarial Mechanics: How Amortization Curves Front-Load Debt Service
Every commercial loan contract balances three interdependent variables: nominal principal, contractual rate, and maturity horizon. In a conventional fixed installment loan, the borrower enjoys payment certainty, yet the internal cash mechanics remain heavily asymmetrical. During the first quartile of a long-term debt schedule, the outstanding balance remains elevated, forcing the vast majority of each installment toward servicing accrued interest rather than building unencumbered equity. Assessing your amortization timeline using a verified Loan Amortization Calculator exposes this mathematical drag, demonstrating why nominal interest rates fail to tell the whole story.
PMT = P × [r(1 + r)ⁿ] / [(1 + r)ⁿ - 1] | Interest_m = Balance_(m-1) × r | Principal_m = PMT - Interest_m
Here, P represents the starting loan principal, r denotes the periodic monthly interest rate (Annual Nominal Rate ÷ 12), and n equals the aggregate number of monthly billing cycles (Years × 12). Because interest in any given month is strictly calculated on the preceding month's ending balance, principal retirement accelerates exponentially as the debt nears maturity.
Simulate Your Amortization Schedule & Balance Trajectory
Test custom borrowing amounts, APR rates, and repayment tenors live on the Loan Amortization Calculator engine to inspect month-by-month principal capture.
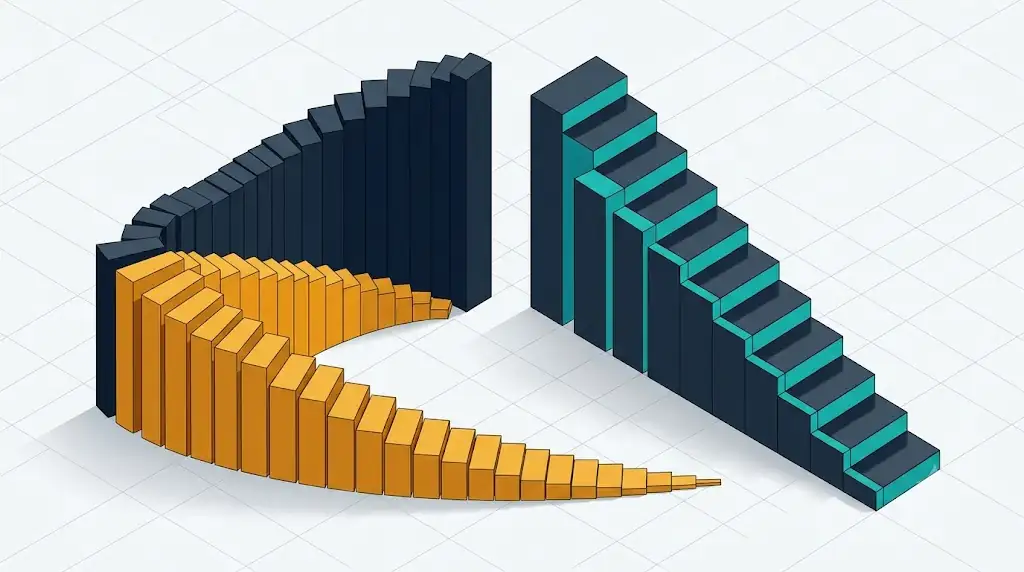
Fixed Monthly Payments vs Equal Principal: The Structural Trade-Off
Retail lending generally divides into two structural conventions: the Annuity Method (constant total payment, variable internal split) and the Equal Principal Method (constant principal reduction, declining total payment). While the annuity model reigns supreme in consumer credit and consumer mortgages due to underwriting predictability, it imposes a punitive cumulative interest penalty. Borrowers assessing personal capacity across broader financing vehicles can benchmark alternatives through a specialized Loan Calculator or examine structured property debt via the Mortgage Calculator.
| Structural Factor | Fixed Monthly Annuity (PMT) | Equal Principal Reduction | Underwriting Impact |
|---|---|---|---|
| Monthly Cash Flow | Identical monthly commitment throughout term | Highest in Month 1, declines linearly every month | Fixed PMT simplifies household budgeting |
| Initial Payment Burden | Standard baseline payment benchmark | 20% to 30% higher cash burden at origination | Equal principal requires higher initial DTI ceiling |
| Lifetime Interest Burden | Maximum interest exposure over loan tenure | 15% to 22% lower aggregate cumulative interest | Equal principal maximizes lifetime wealth retention |
| Equity Accumulation | Slow and concave during initial 5 to 7 years | Linear and immediate balance reduction | Equal principal eliminates underwater equity risk |
30-Year Fixed Mortgage
15-Year Refinance Note
5-Year Vehicle Financing
Prepayment Optimization and Friction Mitigation
Because debt contracts compute daily or monthly interest on current unamortized principal, targeted capital injections immediately compress the downstream interest matrix. Allocating early prepayments directly toward loan principal creates an compounding dividend by extinguishing the base upon which all subsequent interest cycles are calculated. When underwriting personal or vehicle debt via the Auto Loan Calculator, verifying early prepayment flexibility ensures that windfall capital can be deployed without triggering punitive lender clawbacks.
Prepayment Penalty Clauses
Unapplied Escrow Suspense Buffers
Amortization Recast Processing Fees
What differentiates loan amortization recasting from standard debt refinancing?
Refinancing replaces an existing credit note with a completely new loan contract, requiring new underwriting, origination costs, and updated market rates. In contrast, loan recasting preserves your existing interest rate, loan term, and promissory note: you simply submit a significant lump-sum principal prepayment (typically $5,000 or more), and the lender recalculates your monthly PMT downward over the remaining schedule for a minor administrative fee.
Why does a 15-year loan cut aggregate interest by over 60% if the term is only cut by half?
Interest accumulates as a direct function of time and outstanding capital. Because a 15-year schedule forces significantly higher principal redemption from the very first payment cycle, the average balance subject to monthly interest compounding drops drastically faster, creating a non-linear collapse in lifetime financing costs.
How can I verify if my extra payment was credited against principal instead of future interest?
Review the immediate post-transaction billing statement using the Loan Amortization Calculator as a benchmark. Verify that your contractual monthly payment amount remains unchanged while the total ending unpaid principal balance drops by the exact dollar value of your extra capital contribution.
FNCT Editorial Team
Verified MaintainerResearch engineers and algorithm specialists at FNCT.NET, dedicated to building peer-reviewed, zero-log mathematical and developer utilities.