Value-Added Tax (VAT) is calculated forward by multiplying the net pre-tax amount by the statutory rate: Gross Amount = Net Price × (1 + VAT Rate / 100). When extracting tax from a gross commercial invoice, you must apply the reverse calculation formula: Net Price = Gross Amount / (1 + VAT Rate / 100), rather than multiplying the gross figure directly by the tax rate.
- Multiplying a gross receipt directly by the tax percentage distorts margins because the gross base already incorporates 100% principal plus the VAT fraction.
- Businesses remit only the net difference between output tax collected on commercial sales and input tax absorbed on allowable operating purchases.
- Cross-border transactions, asset acquisition debt modeled on a Loan Calculator, and commercial financing structures demand clean tax segmentation to prevent severe cash-flow deficits.
VAT Calculator
Calculate VAT tax amount, gross price, and net amount with standard international tax rates.
The Mathematical Foundations of Direct and Reverse VAT Pricing
In commercial operations, confusing Net Price (pre-tax baseline) with Gross Price (tax-inclusive receipt) remains a leading driver of ledger misstatements, audit sanctions, and margin erosion. When generating outbound B2B quotes, the vendor computes tax forward by scaling the taxable baseline: Gross Amount = Net Price × (1 + VAT Rate / 100). In retail B2C environments or expense auditing, practitioners must work backward from the consumer-facing total. Directly applying a 20% multiplier to a 120 gross invoice calculates tax on the embedded tax itself, falsely inflating liabilities to 24 instead of the authentic statutory obligation of 20.
Forward: Gross = Net × (1 + r) | Reverse: Net = Gross / (1 + r) | VAT Assessed = Gross - Net
Where r represents the decimal tax rate (VAT Rate / 100). In forward mode, the base is normalized to 1.00; adding a 20% levy scales the total multiplier to 1.20. In reverse mode, dividing the inclusive gross total by 1.20 strips away the tax layer, restoring the pure taxable basis. Running your figures through our interactive VAT Calculator eliminates manual rounding discrepancies and confirms ledger symmetry instantly.
Forward B2B Milestone Invoice
10,000 × 1.20.Reverse Retail Procurement Audit
1,100 / 1.10.Simulate Live Forward and Reverse VAT Extractions
Test custom fiscal rates across standard 5%, 10%, and 20% thresholds to isolate statutory liabilities on the verified VAT Calculator engine.
Input Tax Reclamation, Output Liabilities, and Enterprise Cash Flow
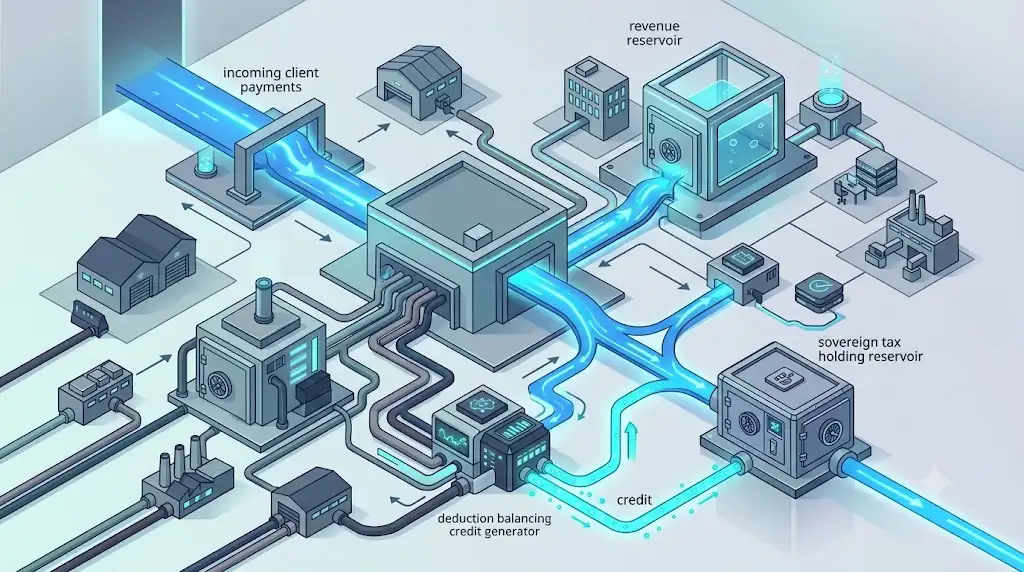
Value-Added Tax is fundamentally structured as a multi-stage consumption levy collected piecemeal throughout supply chains. Corporate entities function as statutory collection conduits rather than ultimate tax bearers. Each reporting period, an enterprise aggregates Output Tax (levied on outgoing commercial revenues) and offsets verified Input Tax (absorbed on verified business expenses, capital gear, and qualified utilities). The net remittance owed to the sovereign revenue authority equals Net VAT Payable = Output Tax - Input Tax. Failing to segregate qualifying input documentation permanently damages operating liquidity.
| Jurisdictional Tier | Statutory Bracket | Qualifying Goods & Commercial Services | Input Credit Recovery Status |
|---|---|---|---|
| Zero-Rated Regime | 0% | Physical export consignments, international cross-border SaaS, international freight | Fully Deductible / Direct Sovereign Refund |
| Reduced Rate Tier | 5% - 9% | Public utilities, essential domestic food staples, municipal transit, basic medical supplies | Standard Input Offsetting Permitted |
| Standard Baseline | 10% - 25% | Commercial hardware, enterprise IT, professional legal advisory, automotive assets | Standard Input Offsetting Permitted |
| Exempt Transactions | 0% (No Tax) | Postal services, residential real estate leases, standard domestic retail financial lending | Blocked / Non-Deductible Input Surcharge |
Reverse Extraction Mathematical Blunder
Unrecovered Capital Asset Input Tax
Exempt vs Zero-Rated Confusion
Strategic Capital Allocation and Capital Expenditure Modeling
Fiscal synchronization extends far beyond basic monthly filings. When financing substantial commercial assets—ranging from logistics fleets to corporate facilities—input tax timing directly governs bridge debt requirements. For instance, commercial property acquisitions frequently demand gross upfront payment, meaning companies carry hundreds of thousands in intermediate tax liabilities until quarterly reconciliations clear. When configuring debt structures using a Mortgage Calculator or structured commercial loans, finance controllers must delineate the tax component from amortizing debt to prevent paying long-term compound interest on recoverable tax credits.
Why is multiplying a gross receipt by 20% mathematically incorrect for a 20% VAT rate?
A tax-inclusive gross amount represents 120% of the underlying net baseline, not 100%. Multiplying 120 by 0.20 calculates 24, whereas the true embedded tax is 20 (120 / 1.20 = 100). This error overstates tax liabilities by 20% of the actual tax amount.
What differentiates zero-rated sales from tax-exempt transactions?
While end customers pay 0% tax in both cases, zero-rated sellers retain full statutory rights to reclaim input tax paid on raw materials and overhead. Sellers of exempt supplies cannot reclaim input tax, turning absorbed VAT into a sunk operating cost.
How should enterprise equipment debt be structured around VAT disbursements?
Capital debt obligations should finance only the net taxable asset value. Recoverable input tax should be funded via short-term revolving working capital lines or bridge loans, preventing long-term interest accrual across extended amortization schedules.
FNCT Editorial Team
Verified MaintainerResearch engineers and algorithm specialists at FNCT.NET, dedicated to building peer-reviewed, zero-log mathematical and developer utilities.